Concert Ticket Insurance Often Won’t Cover Why You Missed
Checkout sells reassurance in one click. The contract pays only when your missed show fits a named event, survives the exclusions, and comes with the required proof.
September 5, 2026 · 8 min read
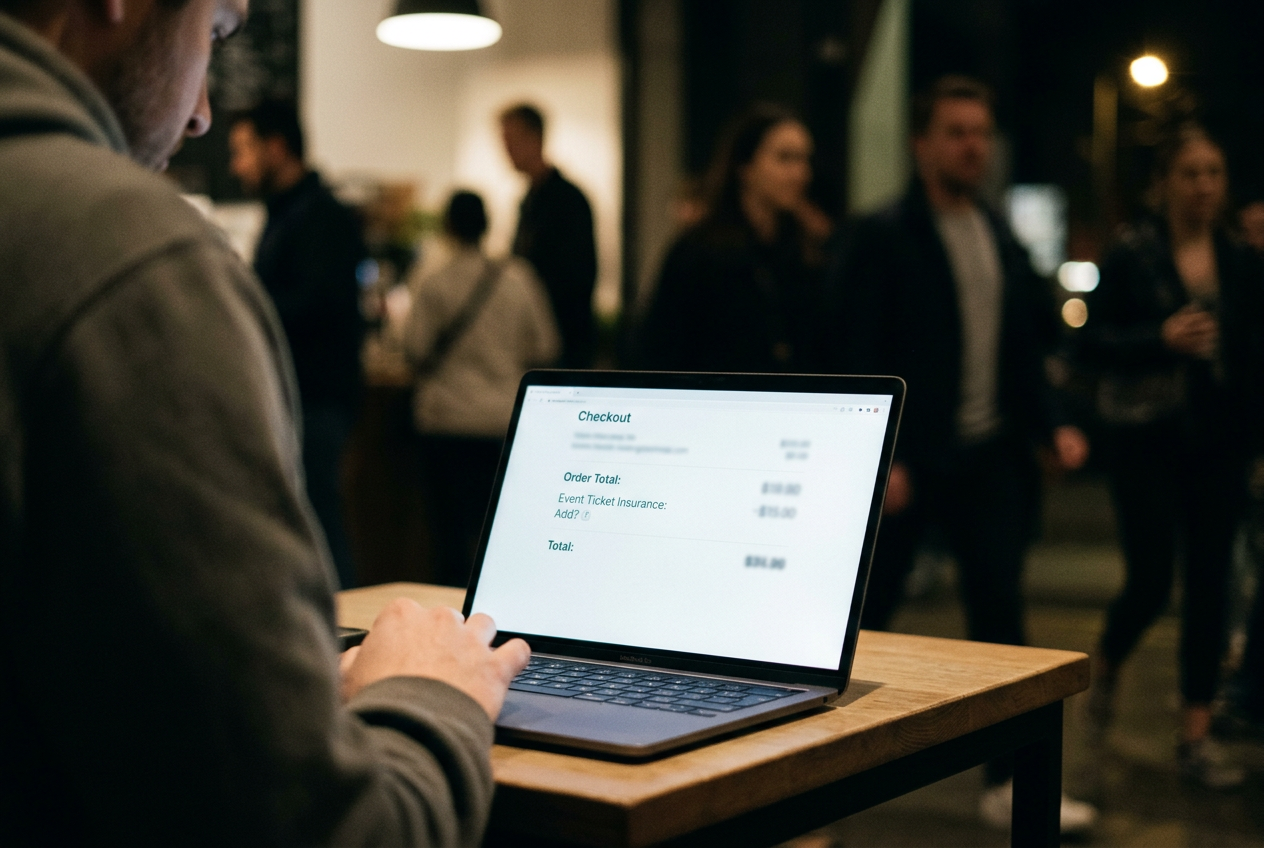
Take the Event Ticket Insurance line attached to a Ticketmaster concert order. It sits beside a premium quoted for that purchase, close enough to the final payment button that declining can feel like betting against your future health, your train, and the sky.
The underlying product is commonly supplied by Allianz Global Assistance. AXS also offers ticket protection through Allianz in the US, while Booking Protect sells refund protection through booking partners under its own terms. Their checkout language varies. The structure does not: you pay now for possible reimbursement later, but only if the reason you miss the event appears in the contract.
That last clause does the work.
Ticket protection is generally named-peril coverage, meaning the policy lists the events that can trigger payment rather than covering every unwanted outcome. Missing the concert is not itself the insured event. A qualifying illness might be. A documented traffic accident on the way might be.
Deciding that the trip has become too expensive will not be, unless the product expressly includes cancellation for any reason.
The add-on is frictionless because the claim is not. Checkout asks for one decision. Claims adjudication, the insurer’s review of whether a loss fits the contract, asks for a cause, a timeline, documents, exclusions, and sometimes records from a doctor or transportation provider.
The contract starts narrower than the sales pitch
Ticketmaster’s customer-facing material describes reimbursement for covered reasons and directs buyers to the specific plan documents for details. Allianz sample certificates then divide the world into covered events, exclusions, limits, and proof requirements. Booking Protect’s public terms do the same, although the vocabulary and covered circumstances differ by product and market.
The important document is not the short description beside the Event Ticket Insurance line. It is the certificate or protection wording issued for that purchase, which can vary by state, seller, event, and plan version. A broad phrase such as “unexpected illness” at checkout may become a much tighter contractual test involving when symptoms began, whether treatment was medically necessary, and what evidence supports the claim.
This gap is not a drafting accident. Insurance works by defining a pool of payable losses tightly enough that collected premiums can cover claims, administration, reserves, and profit. The seller gets a product that raises the order total without making every no-show refundable. The insurer gets a customer at the exact moment that customer feels the ticket is valuable and vulnerable.
The buyer gets conditional protection, though the condition receives far less screen space than the protection.
Public checkout materials do not always disclose the commercial split between ticketing platform and insurer, so it would be reckless to invent one. What is visible is who pays first: the customer. What remains uncertain until a claim is reviewed is whether the insurer pays back.
Illness has to fit the policy’s version of illness
Illness sounds like the cleanest case. It is still conditional.
Allianz event-ticket materials identify covered illness or injury among the possible reasons for reimbursement, subject to the purchased plan. The policy certificate may require that the condition prevent attendance, that a physician advise cancellation, or that the claimant receive an examination or treatment within a specified period. The precise requirement belongs to the issued document, not to a general help page.
That distinction matters for the common illnesses that make a crowded concert a bad idea but do not send someone directly into medical care. A person can be feverish, contagious, exhausted, or experiencing a flare-up serious enough to stay home, yet lack the medical record needed to prove that the policy’s threshold was met. The claim can fail without anyone disputing that the person felt sick.
Preexisting-condition language adds another filter. A preexisting condition is a health issue present before coverage began, as defined by the policy’s own look-back rules. Some plans include waivers under stated conditions. Others exclude losses connected to those conditions.
The buyer cannot infer the answer from the word “illness” on a checkout screen.
The Event Ticket Insurance line therefore does not insure your personal judgment that attending would be unsafe or miserable. It insures a contractually recognized medical event, with whatever documentation that contract demands. Those are different products. Only one was emotionally implied by the timing of the sale.
Transit coverage cares about the cause, not the delay
Transportation trouble gets broken into categories that ordinary travelers rarely use.
Allianz materials may cover circumstances such as a traffic accident, a vehicle breakdown on the way to the event, or certain delays involving a common carrier, which is a commercial transportation service such as an airline or train operator. Booking Protect’s terms can include public-transport failure or vehicle breakdown, again with conditions and evidence requirements.
None of that means “my journey went wrong” is a covered event. Heavy traffic may not qualify without an accident or another listed cause. A missed connection can depend on why the first service failed and whether the policy names that failure. Leaving too little time is a planning problem, not an insured disruption.
A rideshare cancellation is not automatically equivalent to public-transport failure merely because both leave you standing at the curb.
Proof can include an accident report, repair documentation, or confirmation from the transportation operator. A screenshot showing that arrival times kept moving may explain the night perfectly to a friend. The insurer still checks whether it proves a covered cause.
Weather must stop the trip in the approved way
Weather coverage is similarly literal. Bad weather and covered severe weather are not synonyms.
Policy language commonly focuses on weather that prevents travel, causes specified transportation disruption, or leads authorities to close routes. Booking Protect also publishes weather-related provisions tied to warnings or an inability to reach the venue, depending on the applicable terms. Rain, heat, snow, or smoke that makes attendance unpleasant may not be enough while the event continues and transportation remains technically available.
This creates a hard edge around outdoor shows. The organizer can proceed in conditions a buyer considers intolerable. The ticket remains valid. The customer chooses not to go.
Unless the weather meets the policy’s defined trigger, there is no covered loss.
If the organizer cancels or postpones the concert, the ticket seller’s refund or rescheduling rules usually take over. Ticket protection is generally built around the buyer’s inability to attend, not around replacing money that the organizer already owes after calling off the event. The insurer will also avoid paying an amount recoverable elsewhere, because these products reimburse loss rather than create a second payout on the same ticket.
Changed plans are where reassurance runs out
The most common reasons for missing entertainment are often ordinary. A work schedule changes. Childcare disappears. A companion backs out.
The hotel becomes unaffordable. The buyer is tired, anxious about the crowd, or no longer wants the trip.
Some narrow versions of those events can appear in policy language. Allianz materials, for example, may identify employer termination, jury duty, or military obligations as covered situations under an applicable plan. That does not turn a routine shift change or voluntary work commitment into a claim. The named circumstance controls.
“Cancel for any reason” coverage would solve this mismatch by allowing cancellation without fitting a listed cause, usually under separate terms and limits. Standard ticket-protection offers should not be treated as that product unless the contract says so plainly.
The result is blunt. Changed plans are precisely where flexibility has value, but broad flexibility attracts more claims and costs more to insure. Checkout protection stays cheaper and easier to sell by excluding much of the behavior customers casually associate with cancellation.
The useful math has four moving parts
The premium is visible. The probability of collection is not.
A rough expected-value calculation looks like this: the chance you miss the event, multiplied by the chance your reason is covered, multiplied again by the chance you can supply acceptable proof, multiplied by the reimbursable amount, minus the premium. Each contractual filter reduces the value before any payment arrives.
That is why comparing the premium only with the ticket price gives a distorted picture. A modest add-on can look sensible beside an expensive order, yet still be poor value if the buyer’s realistic risks are schedule changes, unreliable informal transportation, or an illness they would manage at home without medical documentation. The product may be more useful to someone whose main risks closely match the listed events and can be independently recorded.
Coverage also does not necessarily follow every dollar attached to the night. The reimbursable amount may center on nonrefundable ticket costs covered by the plan. Transportation, lodging, food, and the time spent pursuing documents can remain with the customer unless the contract expressly includes them.
Return to that Event Ticket Insurance line at Ticketmaster checkout. Its premium is a real number. Its benefit is a conditional number. The interface puts them beside each other as though they are equally knowable, while the second one depends on a policy document most buyers will not open before the countdown, presale pressure, or fear of losing seats pushes them through payment.
That is the mechanism. The add-on sells at the moment of maximum attachment, then evaluates claims through categories designed for insurability rather than through the buyer’s ordinary meaning of “I couldn’t go.”
Questions people ask
Does concert ticket insurance cover being sick?
It can, when illness is a covered event under the issued plan and the claim satisfies its medical and documentation rules. Feeling too sick to attend may not be enough if the certificate requires treatment, a physician’s advice, or evidence that the condition prevented attendance.
Will ticket insurance pay if my train or flight is delayed?
Possibly, but the delay must fit the transportation language in the specific plan. Policies may distinguish a documented common-carrier delay from traffic, a missed rideshare, or a connection lost because the traveler left too little time. Operator confirmation can matter as much as the fact that you arrived late.
Does bad weather qualify for a ticket refund?
Only when the weather meets a covered trigger, such as preventing travel or causing a qualifying transportation disruption. Unpleasant conditions do not necessarily count if the show proceeds. If the organizer cancels, the ticket seller’s cancellation policy usually becomes the first route to a refund.
Can I claim because my plans changed?
Usually not under standard named-peril ticket protection. A specific event such as jury duty may qualify when listed, while a schedule conflict, a companion backing out, or a change of mind generally will not. The controlling answer sits in the certificate issued with that Event Ticket Insurance line.
One update a day
Today's story, in your inbox
One story each morning — no hype, no filler, no algorithm deciding for you.