That Ticketmaster Insurance Box Covers Less Than You Think
Concert ticket insurance is sold after you choose the seat but before you can inspect every exclusion. It covers named emergencies, not the ordinary ways plans collapse.
August 28, 2026 · 8 min read
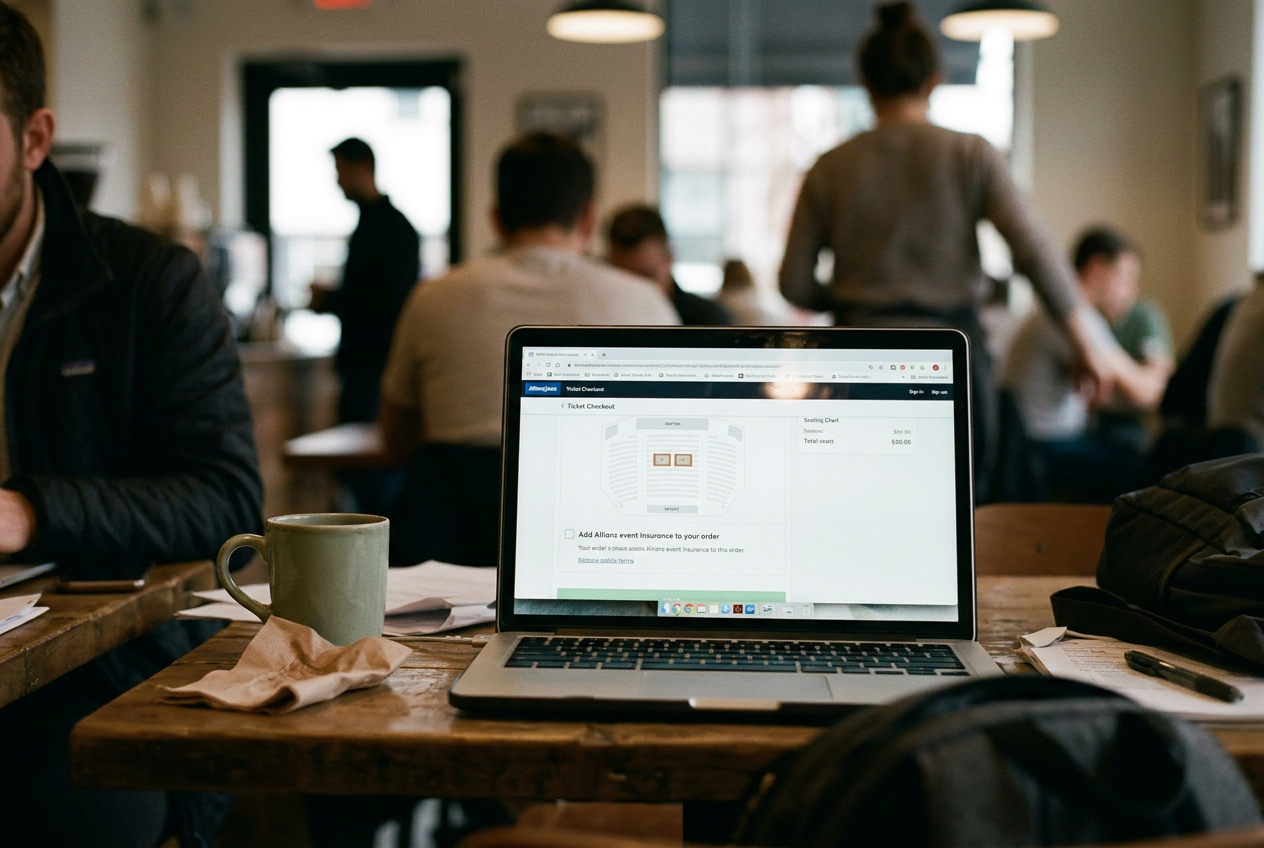
A pair of mobile-only reserved seats is sitting in a Ticketmaster cart. The date works. The view looks tolerable. You have already watched better seats disappear, rejected worse ones and accepted the service charges required to get this far.
Then the checkout presents another decision: add Event Ticket Insurance from Allianz Global Assistance.
This is the moment the product is built for. The seat has been chosen, the clock may be running, and the cost now feels large enough to protect. The offer arrives as reassurance. The contract arrives as a link.
Ticket insurance is a named-peril policy, meaning it pays only when the loss results from a reason specifically listed in the coverage terms. It is not a flexible refund button. If your reason sounds close to a covered event but fails one condition, or if you cannot produce the required evidence, the distinction belongs to you.
The ticket and the policy solve different problems
Ticketmaster’s ticket contract concerns admission to an event. Its published refund rules generally put canceled events back on the organizer and ticket seller, while postponed or rescheduled events depend on the organizer’s decision about refunds. Allianz’s separate product concerns the buyer’s inability to attend an event that is still happening.
That separation explains why insurance keeps appearing beside concert tickets. The ticket seller does not need to make every ticket refundable, which would transfer more scheduling risk back to venues, promoters and artists. The insurer can instead sell limited protection against selected personal emergencies, priced as an add-on and governed by its own certificate of insurance.
The pair of seats remains nonrefundable under the ordinary ticket terms. The insurance does not rewrite those terms. It creates a second contract with a different company, its own definitions, a claims process and exclusions that vary by policy form and state.
Allianz’s public Event Ticket Insurance materials emphasize covered situations such as a qualifying illness or injury, a traffic accident on the way to the venue, a mechanical breakdown, certain carrier delays, jury duty or an unexpected work relocation. Those examples are legible at checkout. The harder question is what each noun requires once it becomes a claim.
Illness has to fit the contract
Feeling too sick to enjoy a concert is not automatically the same as suffering a covered illness. Allianz sample policy forms tie medical claims to conditions such as the illness being disabling enough to prevent attendance and being examined or treated by a physician within the required period. The exact language differs among certificates, which is why the policy attached to the purchase matters more than the summary page.
Documentation does the sorting. A claimant may need a physician’s statement, dates of treatment and confirmation that the medical condition made attendance impossible or medically inadvisable. A headache, a flare-up managed at home or symptoms that never reach a clinician can be real and miserable while remaining hard to prove under the policy.
Pre-existing medical conditions require particular attention. Some forms exclude losses arising from a condition that existed during a specified look-back period, while some plans may waive that exclusion when stated purchase conditions are met. This is not a minor technicality for anyone with a chronic illness. The checkout phrase “covered illness” can sound broad; the certificate may ask when symptoms began, when treatment changed and whether the purchaser qualified for a waiver.
Public-facing Allianz materials say epidemic illness can be covered in some circumstances, including a qualifying COVID-19 diagnosis, but fear of infection is not the same event. Exposure without illness, reluctance to enter a crowded arena or a decision that the health risk no longer feels acceptable generally does not become covered merely because the concern is reasonable.
The policy sells relief from uncertainty while reserving the right to classify that uncertainty later. Your body supplies the event. The claims file decides whether it counts.
A canceled show is usually the seller’s problem
The word “cancellation” causes avoidable confusion because two different cancellations are involved. If you cancel your own night out, the insurance applies only when a listed covered reason caused it. If the artist, promoter or venue cancels the show, Ticketmaster’s published policy generally routes the refund through the original ticket purchase rather than through ticket insurance.
Allianz sample terms commonly exclude losses caused by the event being canceled or abandoned by the organizer, except where a specific benefit says otherwise. That is not necessarily double-dealing. Insurance usually does not reimburse a loss another party already owes. It does mean the product is less expansive than the checkout mood suggests: it protects against certain failures on your side of the transaction, not the disappearance of the concert itself.
Postponement is messier. Ticketmaster states that the event organizer determines whether refunds will be offered for postponed or rescheduled events. A replacement date that conflicts with work, childcare or another trip does not automatically turn into an insured loss, because schedule conflict and change of plans are not usually named covered reasons.
The same pair of mobile tickets can therefore pass between systems. A canceled concert goes to the seller’s refund rules. A qualifying medical emergency goes to the insurer. A rescheduled show you can no longer make may sit between them, with transfer or resale left as the practical exit if the organizer does not authorize refunds and the policy lists no applicable peril.
Travel trouble needs more than lateness
Travel coverage sounds generous until ordinary travel is separated from insured travel. Allianz materials identify events such as a traffic accident, vehicle breakdown or carrier delay as possible covered reasons, but sample certificates attach conditions and require proof. Missing the opening act because traffic moved slowly is not equivalent to being involved in a documented collision. Leaving late is not a carrier delay.
A breakdown claim can require a repair or towing record. A carrier problem can require written confirmation from the airline, rail operator or other travel supplier, along with evidence that the delay met the policy’s definition. Severe weather may matter only through a covered consequence described in the certificate, rather than through a general sense that traveling was unpleasant or risky.
Distance also creates an assumption the policy does not promise to honor. Booking a hotel, train or flight around a concert does not make every related cost part of the insured ticket purchase. Event ticket coverage is generally centered on the nonrefundable ticket amount identified in the plan, not an entire weekend assembled around it. Separate travel arrangements can remain separate losses.
This matters because the checkout offer appears beside the seats, not beside a diagram of every dependency required to use them. The buyer sees one night. The contracts see a ticket, transportation bookings, lodging and personal obligations as distinct transactions with different responsible parties.
Urgency does the selling
Insurance has legitimate uses. A buyer paying a substantial nonrefundable amount may value protection against a narrow set of catastrophes. The problem is the order of information.
By the time the Allianz box appears, the customer has spent attention on seat maps, dynamic availability and the total price. Declining coverage now feels like exposing an asset already mentally owned, even though the buyer has usually seen a short summary rather than the full policy form. Behavioral pressure does work that a patient reading of the exclusions might undo.
Allianz receives the premium and assumes only the risks written into the policy. The public documents reviewed for this piece do not establish how checkout revenue is divided with Ticketmaster, so there is no basis for inventing a commission. What can be seen is the commercial alignment: Ticketmaster keeps the underlying ticket restrictive, Allianz sells a second product against selected consequences of that restriction, and the customer pays both before knowing whether a future problem will fit the claims language.
The insurer also controls the claims gate through documentation and definitions. This does not mean every denied claim is improper. It means the product’s value cannot be judged from the list of friendly examples alone. “Illness” must be read beside medical eligibility.
“Traffic accident” must be read beside evidence. “Cancellation” must be separated into the event organizer’s cancellation and the buyer’s inability to attend.
Return to the pair of reserved seats. The useful comparison is not insurance versus recklessness. It is the premium versus the exact covered reasons, the exclusions, the available organizer refund and the possibility of transfer or resale. If the feared outcome is a routine schedule change, a breakup, lost interest, unsafe-feeling weather or a postponed date that no longer works, the policy may offer no answer at all.
Questions people ask
Does concert ticket insurance let me cancel for any reason?
Usually not. Standard event ticket insurance is generally named-peril coverage, so reimbursement depends on a listed reason such as a qualifying illness, injury or documented transportation problem. Changing your mind, developing a schedule conflict or deciding the trip costs too much will not ordinarily qualify unless the specific certificate says otherwise.
What happens if the artist or venue cancels the concert?
The ticket seller or event organizer generally handles that refund under the ticket terms. Ticketmaster says canceled events are refunded through the original purchase process, while the organizer decides refund availability for many postponed or rescheduled events. Insurance commonly excludes an organizer’s cancellation because another party is responsible for the ticket refund.
What proof does
Allianz require for a ticket insurance claim?
The required documents depend on the reason and policy form. Medical claims may need a physician’s statement and treatment dates; breakdown or traffic claims may need towing, repair, police or carrier records. The receipt for the insured tickets and evidence of the nonrefundable loss are also central to the claims file.
One update a day
Today's story, in your inbox
One story each morning — no hype, no filler, no algorithm deciding for you.