An Etsy Suspension Can Freeze the Money Meant for Rent
Marketplace moderation can stop new sales while payment controls hold money from completed orders. For sellers living bill to bill, an appeal is also an involuntary loan to the platform.
August 25, 2026 · 7 min read
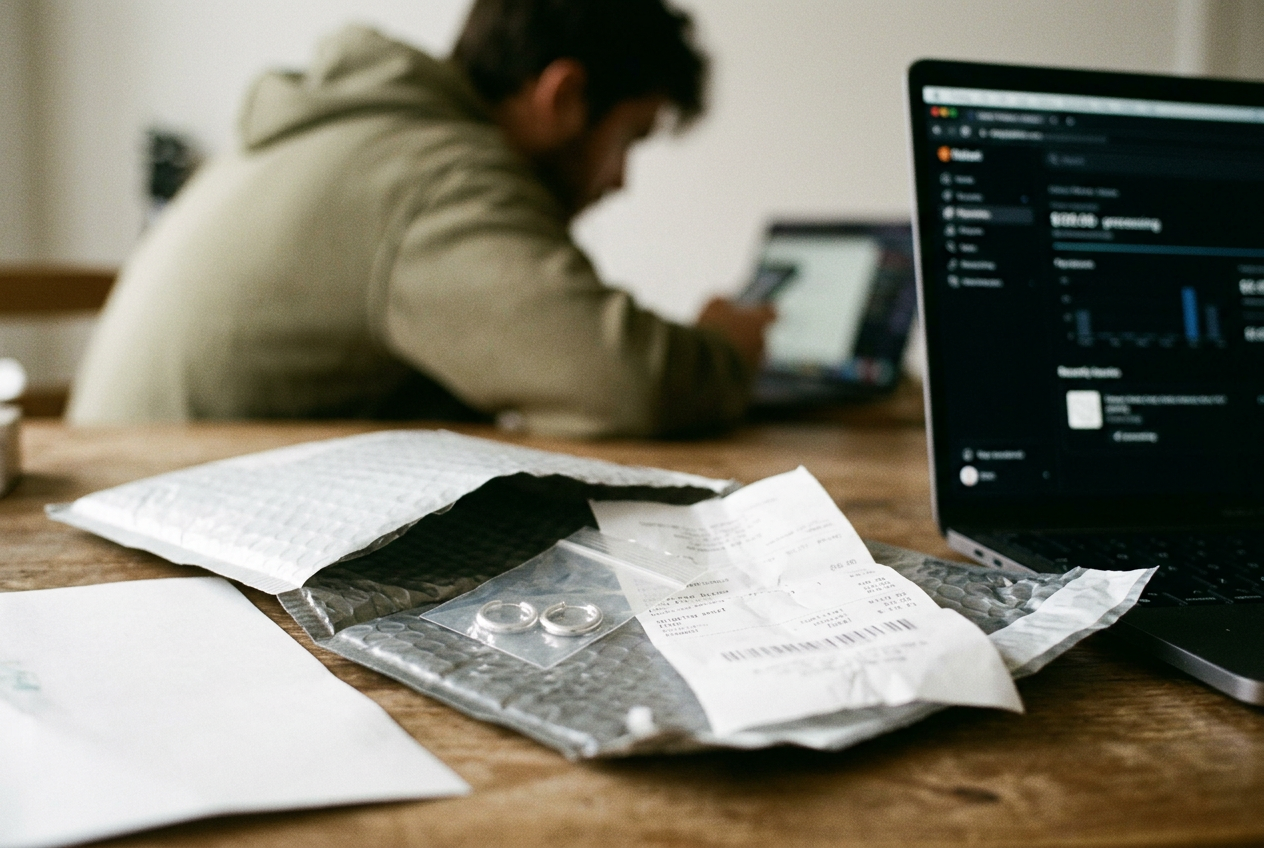
Use one ordinary listing as the unit of analysis: a made-to-order pair of sterling-silver sleeper hoops, bent from wire, closed on a hinge and shipped in a small padded box with tracking. The seller buys the silver before the order arrives. They shape and polish it after the customer pays. Etsy records a sale, deducts its fees and displays a balance that looks like income.
That balance is not the same as cash in a bank account.
Between the customer’s card and the seller’s checking account sits Etsy Payments, the marketplace’s payment system. Etsy can delay a deposit, require identity verification or place money in a payment reserve, which means part of a seller’s balance remains unavailable to cover refunds, chargebacks and other anticipated losses. If the account is suspended while the hoops are in transit, the seller can lose access to future orders and wait for proceeds from work already performed.
This is usually described as trust and safety. The more accurate description is financial governance.
One account, several kinds of control
A marketplace account looks like a shop window, but it bundles several relationships that would once have been separate. Etsy hosts the listing, ranks it in search, processes the customer’s payment and decides when the seller receives the proceeds. It also reviews identity documents, monitors transactions for risk and enforces rules covering prohibited goods, intellectual property and seller conduct.
A problem in one layer can spread across the others. A listing flagged by an automated system may lead to account review. An identity mismatch may interrupt deposits even if the products remain permitted. A surge in orders, late tracking or a pattern that resembles fraud can trigger a reserve without any conclusion that the seller committed fraud.
The platform does not need to prove a case in the way a court would. It needs to manage its exposure under the contract the seller accepted.
For Etsy, that structure is efficient. The company faces customer disputes, card-network rules and regulatory duties, including know-your-customer checks, the identity controls payment businesses use to establish who is receiving money. A marketplace that releases every dollar immediately can be left paying when an order collapses later.
The sterling-silver hoops reveal where the protection lands. Etsy has the customer’s payment. The seller has already spent money on metal, packaging and postage. A reserve leaves the seller financing production while the platform keeps enough cash nearby to protect itself from a future claim.
Risk moves downhill.
The suspension does two jobs
Account suspension is usually understood as a speech or access penalty. The seller cannot publish listings, communicate normally through the marketplace or make new sales. That framework fits a social network, where suspension mainly restricts participation. It is incomplete for a marketplace because the account also contains receivables, meaning money owed from transactions already completed.
Etsy’s public policies give it broad discretion to suspend accounts and manage deposits when it identifies risk or needs more information. Its payment terms also allow reserves and deposit delays, while termination can extend the period during which funds remain held. The exact treatment depends on the account and the reason for review, which is part of the problem: the seller can see that money is unavailable without receiving a case file explaining the model, signal or document that produced the decision.
The practical sequence is blunt. A customer orders the hoops. The card payment clears. The seller buys or has already bought the silver, performs the labor and purchases postage.
A platform review then interrupts the account. Search traffic disappears immediately, but the pending balance does not necessarily leave with the same speed.
A seller paid through a conventional job can dispute discipline while wages already deposited remain in their bank. A marketplace seller may have to dispute moderation while the institution hearing the appeal also controls the transfer of earnings. That concentration changes the stakes. The platform is landlord of the shop, payment intermediary and first court of appeal, though it owes the seller none of the procedural guarantees those public-sounding roles imply.
Identity checks are not clerical
Identity verification is often presented as a form to complete. In practice, it can become a recurring condition of payment, especially when a seller’s legal name, tax information, bank details or address do not match across systems. A changed surname, expired document or bank account held under a business name can turn a routine check into a loop.
The underlying obligation is real. Payment companies must comply with financial rules and sanctions controls, while marketplaces have strong reasons to stop stolen identities and fraudulent shops. Yet the interface converts that institutional duty into a private administrative burden. The seller uploads a document, waits for review and may receive another request that does not explain which field failed.
The platform carries out compliance at scale; the individual absorbs the uncertainty one bill at a time.
Public reporting on marketplace sellers repeatedly shows the same imbalance even when the details differ: support channels offer standardized replies, review periods remain unclear and escalation is difficult without outside attention. The process may eventually restore the account. Rent does not wait for eventual accuracy.
This is why the distinction between a ban and a payout hold matters. Losing next week’s sales is a forecast problem. Losing access to last week’s proceeds is a liquidity problem, which means the seller has value on paper but not enough available cash to meet an immediate obligation. The hoops have been delivered.
The revenue exists. The money cannot yet do the job the seller assigned to it.
Reserves turn sellers into involuntary lenders
Etsy drew sustained criticism in 2023 after sellers and public reporting documented payment reserves that could withhold a large share of sales for extended periods. The company later reduced the amount withheld for many affected sellers. That revision mattered, but it did not alter the governing principle: the marketplace can decide that a seller’s completed transactions should finance the marketplace’s protection against possible future losses.
A reserve is not necessarily a seizure. The money may be released after tracking shows an order in transit or after the designated holding period ends. That distinction will matter greatly to a lawyer and very little to a landlord expecting payment this week.
The policy also rewards sellers who can afford patience. A larger operation may carry working capital, the cash used to buy supplies and cover expenses before revenue becomes available. A gig worker funding orders from the last batch of payouts cannot. If the proceeds from the silver hoops remain reserved, the next coil of wire goes on a credit card, another order ships late or the shop pauses.
Each response can produce new risk signals, allowing a cash shortage created by the platform to resemble evidence that the seller was risky all along.
This feedback loop is easy to miss when moderation and payments are discussed by separate teams. Trust and safety sees a suspicious account. Payments sees potential chargebacks. Support sees a ticket.
The seller sees one institution holding the rent.
An appeal clock is an economic decision
Platforms tend to measure appeals through queues, review targets and case resolution. Sellers experience them through due dates. A response that arrives within a period the company considers reasonable can still cross a rent deadline, a utility cutoff or the date a card begins charging interest.
Speed is therefore part of the ruling. An appeal system can reverse a false positive and still inflict the penalty if the correction comes after the seller had to borrow money or miss a payment. The company may restore the listing for the sterling-silver hoops without accounting for the week when the shop could not trade, the materials that sat unused or the fees attached to emergency credit.
A meaningful alternative would separate more of the payment decision from the moderation decision. Platforms could release undisputed proceeds from tracked, completed orders while holding only the amount tied to identified exposure; show sellers the category of evidence that triggered review; and provide a faster human escalation route when a payout hold threatens money already earned. Those protections would cost the marketplace. Human review is expensive, narrower reserves leave the company carrying more risk, and detailed explanations may help determined fraudsters adapt.
That cost is the point. The current design does not eliminate risk. It assigns the risk to the party with less cash, less information and no power to change the contract.
The padded box containing the hoops may reach the customer before the appeal reaches a reviewer. Delivery confirms that the seller’s labor crossed the country. It does not make the proceeds available for rent.
Questions people ask
Can
Etsy hold money after suspending a seller account?
Yes. Etsy’s public terms allow it to delay deposits, establish reserves and hold funds when it identifies financial or account risk. Suspension can stop new sales while pending proceeds remain subject to those controls, so money shown in the payment account may not be available to transfer.
Why does
Etsy ask sellers to verify their identity again?
Marketplaces and payment processors must establish who receives funds and may repeat checks after account details change or systems detect a mismatch. A failed check does not always mean fraud, but it can interrupt payouts while the seller submits documents and waits for review.
What is a payment reserve on Etsy?
A payment reserve keeps part of a seller’s proceeds unavailable to cover possible refunds, disputes or chargebacks. The money may be released after valid tracking appears or a holding period passes, but the seller still has to fund materials, postage and household bills during the delay.
Why can an appeal take longer than a seller can afford?
Platform review queues follow internal risk and staffing priorities rather than a seller’s bill calendar. Even a successful appeal can arrive after rent is due, which means procedural correction does not undo borrowing costs, missed payments or the sales lost while the shop remained unavailable.
One update a day
Today's story, in your inbox
One story each morning — no hype, no filler, no algorithm deciding for you.